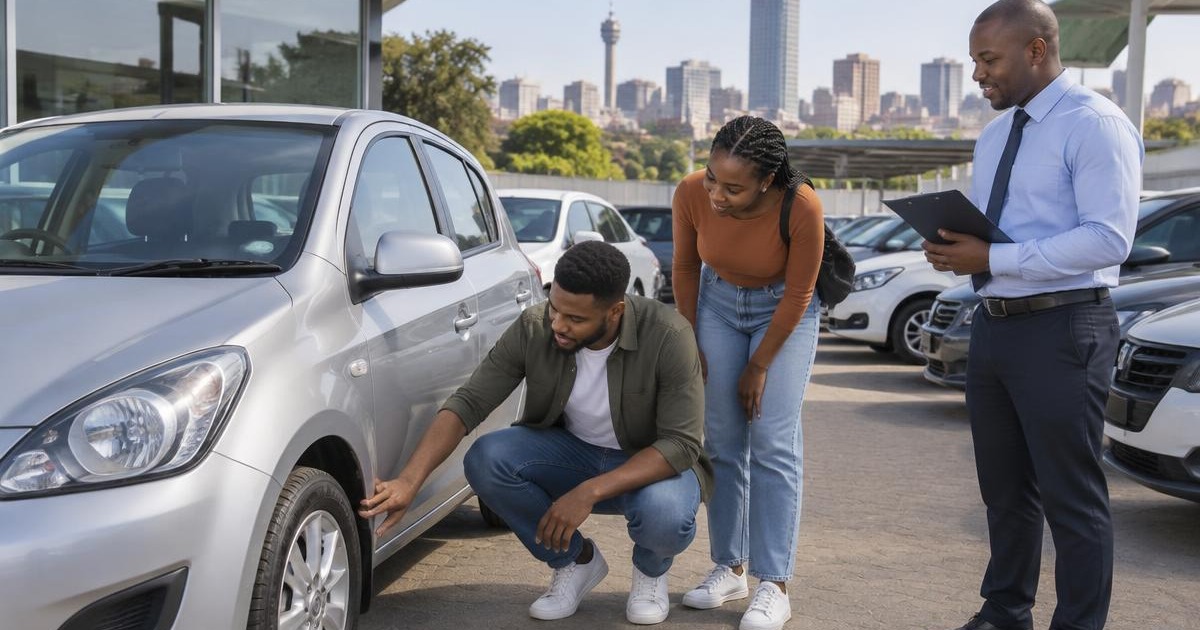
Explaining the Process of Buying a Car
Buying a car in South Africa involves more than choosing a model and paying the advertised price. You need to decide what you can afford every month, check the vehicle and its paperwork, understand the contract, arrange insurance, and make sure ownership is correctly recorded on eNaTIS.
This guide covers new and second-hand cars bought from a dealer, a private seller, or an auction. It also explains the costs that are easy to overlook.
Quick facts
- Compare the total cost of ownership, not only the instalment or purchase price.
- A roadworthy certificate is a safety check, not a guarantee that the engine, gearbox, electronics, or other expensive parts are sound.
- Dealer purchases generally receive Consumer Protection Act protection; an ordinary once-off private sale generally does not give you the same protection.
- For a used vehicle, the seller and buyer each have eNaTIS paperwork to complete. The change must be reported within 21 days.
- Auction bids can become binding immediately. Read the rules and calculate all added charges before bidding.
Before you start: work out what you can really afford
Start with a monthly transport budget, not the largest instalment a lender may approve. Include:
- the cash price or monthly finance instalment;
- comprehensive insurance, if required by the lender or sensible for your risk;
- fuel or charging costs;
- licence renewal;
- servicing, maintenance, tyres and unexpected repairs;
- parking, tolls and tracking subscriptions where applicable; and
- a reserve for an insurance excess after a claim.
Ask insurers for quotes on the exact model before signing. Insurance prices can differ greatly depending on the driver, address, security, claims history and vehicle. A cheaper car can sometimes cost more to insure or maintain.
If financing, compare the total amount repayable, interest rate, deposit, repayment period, balloon or residual payment, initiation fee, monthly service fee, and any products added to the agreement. A low monthly instalment may be created by a longer term or a large final balloon payment, both of which increase risk and often increase the total paid.
New, dealer-used, private sale or auction?
Buying from a motor dealer
A dealer can arrange finance, registration and delivery, and may offer a manufacturer warranty, dealer warranty, service plan or maintenance plan. Ask which benefits are included in the advertised price and which are optional.
The Consumer Protection Act generally applies when a dealer supplies a vehicle in the ordinary course of business. The vehicle must be reasonably suitable, of good quality and usable for a reasonable time, taking its age, price, mileage and disclosed condition into account. This does not make every used car perfect, and it does not replace careful inspection. Get every promise and disclosed defect in writing.
If a dispute cannot be resolved with the dealer, the Motor Industry Ombudsman of South Africa (MIOSA) handles automotive-industry complaints under the Automotive Industry Code.
Buying privately
A private sale may cost less, but you usually do not receive the same Consumer Protection Act protection as when buying from a dealer. Confirm that the seller is the registered owner or is legally authorised by the titleholder to sell. If finance is still owing, do not simply pay the seller and assume the bank's interest disappears. Arrange a settlement and release process that the finance provider confirms.
Use a written sale agreement recording the parties, vehicle details, price, payment method, known defects, items included, handover date, odometer reading and responsibility for the roadworthy and transfer costs. Never rely only on a WhatsApp conversation.
Buying at auction
At an auction, you bid under the auction house's published rules. Registration may require identification and a bidder's deposit. The highest bid may still be subject to a reserve price or seller confirmation, depending on the rules.
Before bidding:
- Get and read the rules of auction. Check when a bid becomes binding, whether the sale is subject to confirmation, and how long you have to pay and collect.
- Inspect the car during the viewing period. Test drives may not be allowed. If possible, take a qualified mechanic or vehicle assessor.
- Calculate your all-in limit. Add the buyer's commission, VAT where applicable, documentation or administration charges, registration, licence and roadworthy costs, transport or towing, storage penalties, and immediate repairs.
- Check what paperwork is supplied. Confirm the registration certificate, NCO process, keys, service records and any police-clearance requirement.
- Understand the condition terms. Vehicles are often sold as-is, and section 55's implied-quality right does not apply in the same way to goods bought at auction. Other Consumer Protection Act auction rules and protections still matter. Do not assume you can return the car because you later find a defect.
Warning: Never bid first and inspect later. Once the auctioneer accepts a binding bid under the rules, changing your mind can cost your deposit and may expose you to further claims or fees.
Step-by-step: how to buy a car in South Africa
1. Choose a realistic vehicle and budget
Shortlist cars that meet your actual needs. Compare safety features, fuel use, insurance, tyre prices, parts availability, service intervals, resale value and theft risk. For finance, get pre-approval from a registered credit provider so you can compare offers without focusing only on the dealer's monthly figure.
2. Verify the seller, vehicle and paperwork
Match the VIN and engine number on the car to the registration certificate. Check the seller's identity against the registered owner or obtain proof that the titleholder authorised the sale. Ask for the service history and invoices, and consider a reputable vehicle-history check for finance, theft, write-off or accident indicators. A history report is useful but is not a substitute for physical inspection.
Do not pay a deposit merely because a seller creates urgency. Be suspicious if the price is far below the market, the seller refuses an inspection, the registration document is missing, or payment must go to an unrelated person.
3. Inspect and test-drive the car
View the vehicle in daylight. Check panel gaps, paint differences, overspray, rust, glass, lights, warning lamps, fluid leaks, tyre condition and whether all keys and accessories work. Start the engine from cold if possible and test the clutch or automatic transmission, brakes, steering, suspension, air conditioning and electronics.
Pay for an independent inspection before committing, especially for a private or auction purchase. A roadworthy test checks prescribed safety items; it is not a full mechanical warranty.
4. Ask for a written, itemised quote
For a dealer sale, the quote should separate the vehicle price, optional extras, delivery or administration items, licence and registration costs, finance charges, warranties, service plans, tracking devices and insurance products. Ask the dealer to remove anything you did not choose.
For a private sale, agree in writing who pays for the roadworthy certificate, ownership transfer, licence arrears and any repairs identified before handover.
5. Compare finance properly
Under the National Credit Act, the credit provider must assess affordability and give you pre-agreement disclosure. Read the quotation before accepting it. Compare:
- fixed or linked/variable interest rate;
- deposit and trade-in value;
- number of instalments;
- total cost of credit and total amount repayable;
- initiation and monthly service fees;
- balloon or residual amount due at the end;
- credit-life insurance and other optional products; and
- early-settlement and default terms.
Do not sign blank forms or allow anyone to inflate your income or reduce your expenses on the application. Keep a copy of everything signed.
6. Sign only after checking the complete contract
Make sure the year, model, VIN, mileage, price, deposit, finance terms, extras, warranty, service plan, disclosed defects and delivery promises are correct. Put conditions such as finance approval or an independent inspection in writing. Ask questions before signing; verbal promises are difficult to prove.
7. Pay safely and arrange insurance
Confirm bank details independently before transferring money. Avoid cash handovers and never send money to an account that does not match the seller or verified business without a documented reason. For a financed car, comprehensive insurance is normally required before delivery. Even for a cash purchase, driving away uninsured can create a major financial risk.
8. Complete delivery checks
At collection, compare the vehicle with the agreement. Record the mileage and condition, check both keys, spare wheel or repair kit, tools, licence disc, manuals, service record, warranty documents and proof of payment. Photograph the vehicle and documents. Do not sign a delivery note saying everything is correct if it is not.
9. Complete the change of ownership
For a used-car sale, the seller submits the Notification of Change of Ownership form (NCO), while the buyer uses the Application for Registration and Licensing of Motor Vehicle form (RLV). The change must be reported within 21 days. A financed vehicle normally records the bank as titleholder until the debt is settled.
Use our vehicle change-of-ownership guide for the documents, roadworthy process and registration steps.
Car-buying fees and hidden costs
There is no single national total because the deal, lender, province, vehicle and auction house affect the cost.
| Cost | When it applies | What to check |
|---|---|---|
| Deposit | Cash or finance deal | Whether it reduces the capital amount and when it becomes non-refundable |
| Interest | Financed purchase | Rate type, term, total amount repayable and effect of a balloon payment |
| Finance initiation and service fees | Credit agreement | Current regulated amounts and whether they appear in the quotation |
| Balloon/residual payment | Some finance agreements | Large final amount, refinancing risk and likely vehicle value at the end |
| Dealer delivery/admin or “on-the-road” items | Some dealer deals | Exact itemisation, whether optional, and whether included in financed principal debt |
| Registration and licence | New registration or ownership transfer | Provincial fee, vehicle tare and any outstanding licence amount |
| Roadworthy test | Many used-vehicle transfers | Who pays, retest costs and expiry timing |
| Insurance and excess | Before delivery and throughout ownership | Monthly premium, excess, exclusions and tracking/security requirements |
| Tracking device | Sometimes required by insurer/lender | Installation, monthly subscription and cancellation terms |
| Warranty/service/maintenance plan | New or used dealer vehicle | What is covered, exclusions, claim limits and whether it is optional |
| Immediate maintenance | Especially used and auction cars | Service, cambelt/chain advice, battery, brakes, fluids and tyres |
| Auction buyer's commission | Auction purchases | Percentage or fixed fee and whether VAT is added |
| Auction documentation, storage and collection | Auction purchases | Payment deadline, late collection charges and transport if the car cannot be driven |
| Fuel, tolls and parking | Ongoing | Your real monthly use, not a generic estimate |
Do not finance optional extras automatically. Adding a warranty, tracking contract or service plan to the loan means you may also pay interest on it for years.
What to ask when buying a second-hand car
Ask the seller these questions and request documents where an answer can be proved:
Ownership and legal status
- Are you the registered owner, and can I see your ID and original registration certificate?
- Is a bank or another person still the titleholder? If so, what is the verified settlement process?
- Are there outstanding licence fees, traffic-related blocks, police marks, or other restrictions that could delay transfer?
- Do the VIN and engine numbers match the registration papers?
- Has the vehicle ever been stolen and recovered, written off, rebuilt or declared uneconomical to repair?
Condition and history
- Has it been in an accident, flooded, or had structural or airbag repairs?
- Is the displayed mileage genuine, and what records support it?
- Is there a complete service history? Which dealer or workshop can confirm it?
- What currently does not work, and which defects have been repaired recently?
- When were the tyres, brakes, battery and major timing components last replaced or checked?
- Are there outstanding safety recalls for this VIN?
- May my independent mechanic inspect it and perform a diagnostic scan?
What comes with the car
- Are both keys, manuals, spare wheel or repair kit, tools and security codes included?
- Is any manufacturer warranty, service plan or maintenance plan still valid and transferable?
- Which accessories are included in the written price?
- Who will provide and pay for the roadworthy certificate and transfer documents?
The deal itself
- What is the full price after every fee and optional product?
- Is the deposit refundable if finance or inspection fails, and is that written into the agreement?
- If buying from a dealer, which defects are disclosed on the condition report?
- When does risk pass to me, and may I inspect the car again before final delivery?
If the seller refuses basic proof or an independent inspection, walk away.
Common mistakes to avoid
- Choosing a car by monthly instalment without comparing the total amount repayable.
- Ignoring a balloon payment until the end of the agreement.
- Treating a roadworthy certificate as a mechanical inspection.
- Paying before verifying the seller, titleholder, VIN and registration certificate.
- Accepting verbal promises about repairs, warranties or included extras.
- Buying privately without a signed sale agreement and proof of payment.
- Bidding at auction without adding commission, VAT, documentation, transport and repair costs.
- Driving away without insurance or without checking the delivery condition.
- Assuming the dealer or seller completed the eNaTIS transfer without keeping proof.
If something goes wrong
Write to the dealer or supplier promptly, explain the problem and the outcome you want, and keep the agreement, advertisement, condition report, inspection report, invoices, messages and photographs. If the dealer does not resolve an automotive dispute, consider lodging a complaint with MIOSA. Credit-agreement complaints may also fall within the National Credit Regulator or relevant credit ombud process.
Private-sale disputes often depend on the contract, what was disclosed and whether there was fraud or misrepresentation. Get legal advice before spending heavily on a dispute.
Sources
- South African Government — Consumer Protection Act 68 of 2008
- South African Government — Consumer Protection Act regulations, including auction rules
- South African Government — National Credit Act 34 of 2005
- South African Government — Change owner or titleholder particulars for a vehicle
- NaTIS — Road traffic forms, including NCO and RLV
- South African Government — Roadworthy certificate guidance
- National Credit Regulator — consumer information
- Motor Industry Ombudsman of South Africa — consumer complaints and Automotive Industry Code
This guide provides general information, not legal, financial or mechanical advice. Charges, finance terms and auction conditions differ. Confirm the current requirements with the seller, lender, insurer, auction house and registering authority before paying or bidding.