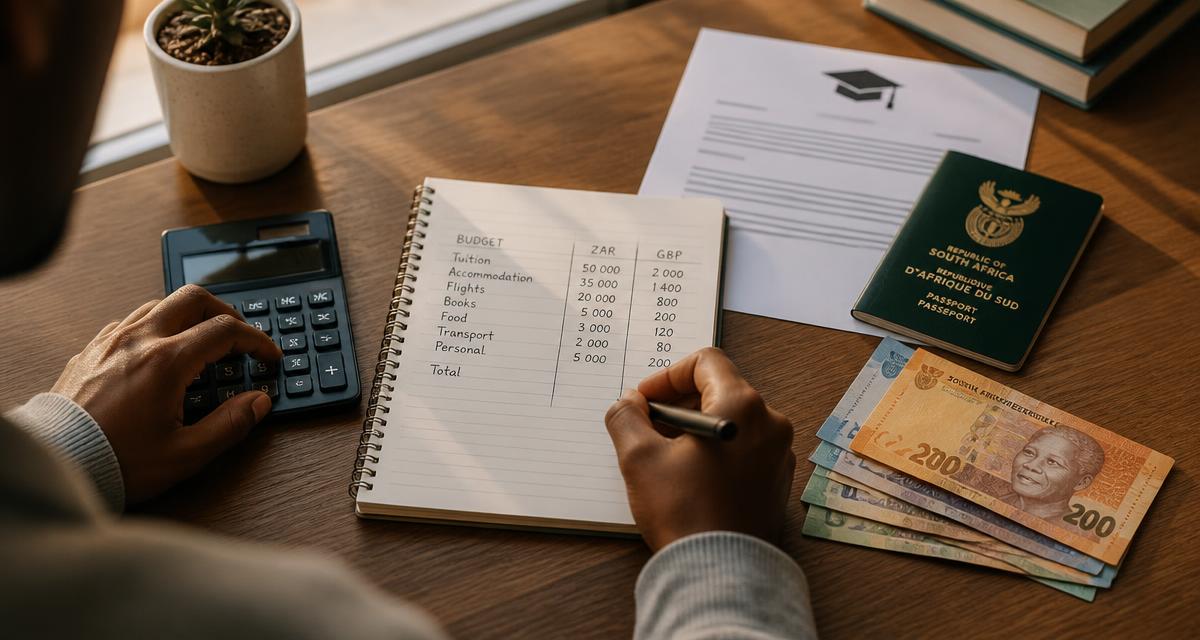
Student Loans and Funding for Studying Abroad as a South African
Funding is where most study-abroad plans succeed or fail. Almost every student visa requires proof that you can pay tuition plus living costs for at least the first year, so your funding plan must be in place before you apply — not after you get the offer. This guide explains the realistic options for South Africans: NSFAS (and why it does not apply overseas), scholarships and bursaries, bank student loans, and work-study options. For the full application process, read the study-abroad overview.
First: does NSFAS fund study abroad?
No. NSFAS (the National Student Financial Aid Scheme) funds qualifying students at South African public universities and TVET colleges only. It does not pay for tuition, travel or living costs at foreign institutions. If you are currently NSFAS-funded and plan to study overseas, budget as if you have no NSFAS support.
Two DHET-linked programmes are the exception, not the rule: occasional international scholarship calls administered by DHET (often through bilateral agreements with other governments) do fund South Africans abroad, and the NRF funds certain postgraduate research, sometimes with mobility support. Watch DHET's official bursaries page for calls, and treat anything advertised on social media as a scam until verified on a .gov.za website.
Scholarships and bursaries
This is the cheapest money — it does not have to be repaid — but it is also the most competitive, and deadlines usually close months before course applications.
- University scholarships for international students. Most universities in the UK, USA and Australia offer merit scholarships that discount tuition for strong applicants. These are listed on each university's international fees page and are often automatic on application or need a short separate form.
- Chevening (UK). UK government scholarships for one-year master's degrees, covering tuition, living costs and flights. South Africa has a strong Chevening track record; applications open around August each year.
- Fulbright (USA). Funds South African graduates for master's or PhD study in the USA, administered in South Africa through the Fulbright commission (based at the US Embassy).
- Commonwealth Scholarships (UK). For master's and PhD candidates from Commonwealth countries, including South Africa, usually aimed at development-focused study.
- Australia Awards. Australian government scholarships for postgraduate study, with priority fields that change by year.
- Mandela Rhodes and Rhodes Scholarships. Prestigious postgraduate awards — Rhodes for study at Oxford, Mandela Rhodes for postgraduate study at South African institutions (useful if you stay local for an honours year first).
- Private bursaries. Some South African companies, trusts and professional bodies fund overseas study in their field — check bursary directories and ask the university's funding office for a list.
Practical tip: scholarship results arrive before visa applications in most countries, and a scholarship letter counts as proof of funds. Apply to several in parallel rather than betting on one.
Bank student loans in South Africa
South African banks — Standard Bank, Nedbank, Absa, FNB and Capitec, plus specialists such as Fundi — offer student loans, but with an important catch: most are designed for study at South African institutions. For overseas study you will usually be looking at a personal loan or a secured loan (for example against a parent's property or investments), not a classic student loan. What to know:
- Loans almost always require a South African surety (co-signer) — usually a parent or guardian with a steady income — because the student has no credit history and will be abroad.
- Interest on unsecured loans is high relative to prime; repay over the shortest term you can manage.
- Some lenders release funds in tranches against proof of enrolment each year.
- A loan approval letter in your name or your sponsor's name can support proof of funds, but some visa authorities prefer to see cash in an account — check the specific rules (the UK, for example, accepts official student loans but requires them to meet strict conditions and wants the money held for 28 days).
- Borrow only what you need: the rand exchange rate means repayments get more expensive if the rand weakens while you earn in rands.
International student loans
Some foreign lenders (for example Prodigy Finance and MPOWER Financing) lend to international students for specific universities and programmes, often without a co-signer, especially for postgraduate business, engineering and STEM degrees. Check whether your chosen university is on their approved list, compare the annual percentage rate (APR) rather than the headline rate, and remember you will be repaying in foreign currency.
Work-study and part-time work
Part-time work helps with living costs but cannot fund tuition — and visa officers know it. Never present expected part-time earnings as proof of funds.
- UK: up to 20 hours a week during term, full time in vacations, for degree-level students.
- USA (F-1): on-campus work only, up to 20 hours a week during term; off-campus work needs authorisation (CPT/OPT).
- Australia: capped fortnightly hours during term (currently 48 hours per fortnight) and unrestricted hours in scheduled breaks.
- Assistantships (USA): graduate teaching and research assistantships can waive tuition and pay a stipend — a genuine full-funding route for strong postgraduate applicants.
Getting the money out of South Africa
South Africans moving study funds abroad use the SARS single discretionary allowance (up to R1 million per calendar year without a tax clearance) or the foreign investment allowance (up to R10 million a year, requiring SARS approval for international transfers). Speak to your bank's foreign-exchange desk early — transfers take days, require supporting documents, and the exchange rate on transfer day can move your budget by thousands of rand.
A sensible funding sequence
- Price the full first year: tuition, visa fees, health cover, flights and realistic rent.
- Apply for every scholarship you qualify for — first, because they close early.
- Fill the remaining gap with savings, family support and, only if necessary, a loan.
- Keep proof for each source in one place: scholarship letters, loan approval, bank statements covering the required holding period.
- Only book flights after the visa is granted.
Common funding mistakes
- Assuming NSFAS or a SA bursary will transfer to an overseas university — it will not.
- Showing a lump sum deposited days before applying; visa offices want explained, seasoned funds.
- Depending on part-time work income to satisfy the visa's financial requirement.
- Ignoring the exchange rate; budget in the destination's currency with a buffer of at least 5–10%.
- Paying "scholarship agents" upfront fees. Legitimate scholarships never charge to apply.
Sources
- NSFAS — funding scope for public SA institutions (nsfas.org.za)
- DHET — international scholarships and bursary calls (dhet.gov.za)
- Chevening Scholarships (chevening.org)
- Fulbright South Africa (fulbright.org.za)
- Commonwealth Scholarships (cscuk.fcdo.gov.uk)
- Australia Awards (australiaawards.gov.au)
- UK Home Office — Student visa money rules (gov.uk/student-visa/money)
- SARS — allowances for transferring funds abroad (sars.gov.za)
This is general information, not financial or immigration advice. Scholarship rounds, loan terms and exchange-control rules change regularly — confirm everything on official websites and with a registered financial adviser before borrowing.